Every Shoreline
Has a Number.
Defensible valuations for oceanfront estates, trust settlements, jumbo underwriting, and litigation where the tide line is the most volatile variable on the balance sheet.
From Gulf-Side Condo
to $40M Compound.
Each assignment below is a real engagement — the challenge, the method, and the number that moved the transaction forward. Click any card to read the full case.
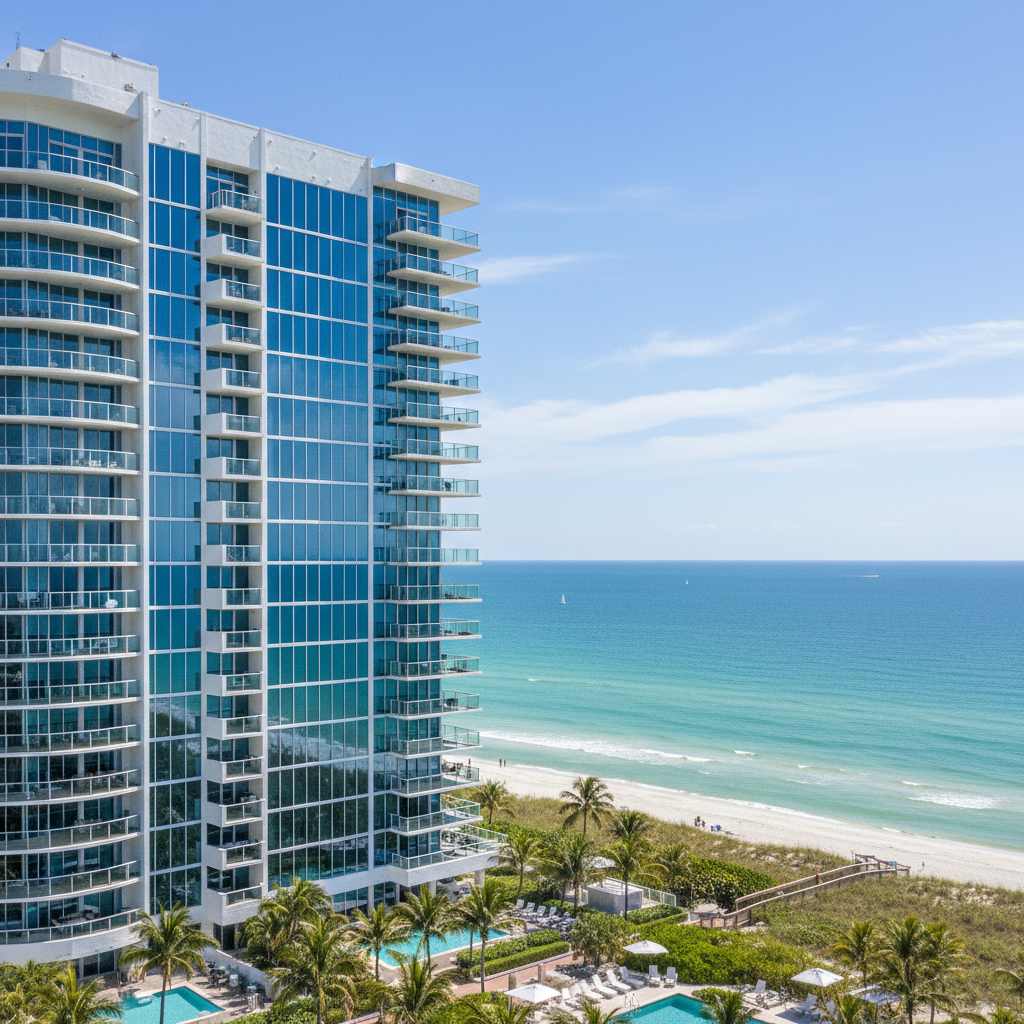
Gulf-Side Condo, FEMA Zone Dispute
A lender flagged the unit after FEMA's preliminary flood-map revision reclassified the building from Zone X to Zone AE, triggering mandatory flood insurance that would have pushed the borrower's DTI above underwriting limits.
We cross-referenced FEMA's Letter of Map Amendment database, obtained certified elevation certificates, and commissioned a licensed surveyor to verify the finished-floor elevation against the revised Base Flood Elevation. Comparable sales were adjusted for flood-zone designation as a discrete line-item variable.
Appraisal supported a successful LOMA application. Flood insurance requirement removed. Loan closed at the original rate.
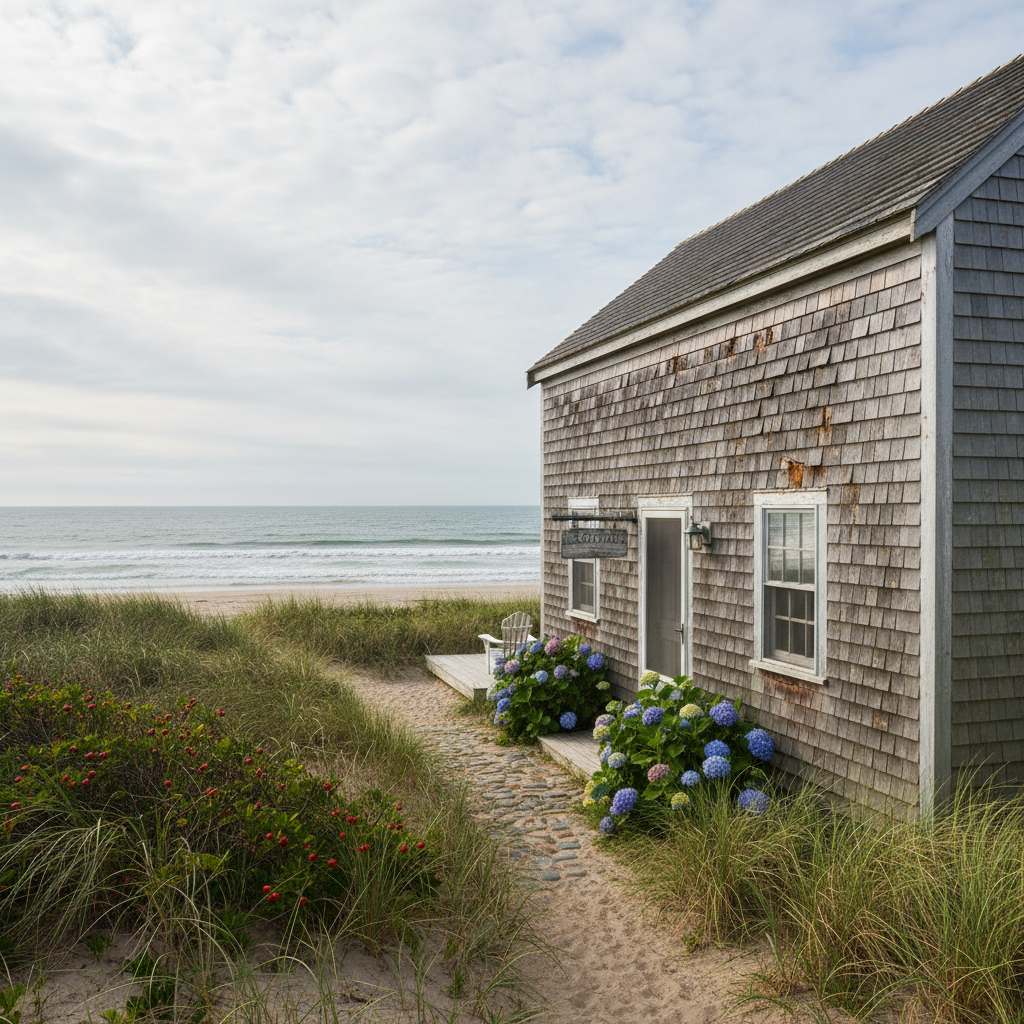
Trust Settlement, Erosion Diminution
A Boston estate attorney needed a value that accounted for 18 feet of documented shoreline recession over the prior decade. Two beneficiaries disputed whether the erosion constituted a compensable diminution or a natural condition already priced into market.
LIDAR elevation modeling overlaid on USGS historical shoreline data quantified the loss. We applied a paired-sales analysis isolating bluff-setback distance as a regression variable across 14 Nantucket transactions, arriving at a per-linear-foot erosion penalty coefficient.
Diminution valued at $340,000. Estate settled without litigation. Both beneficiaries accepted the figure.
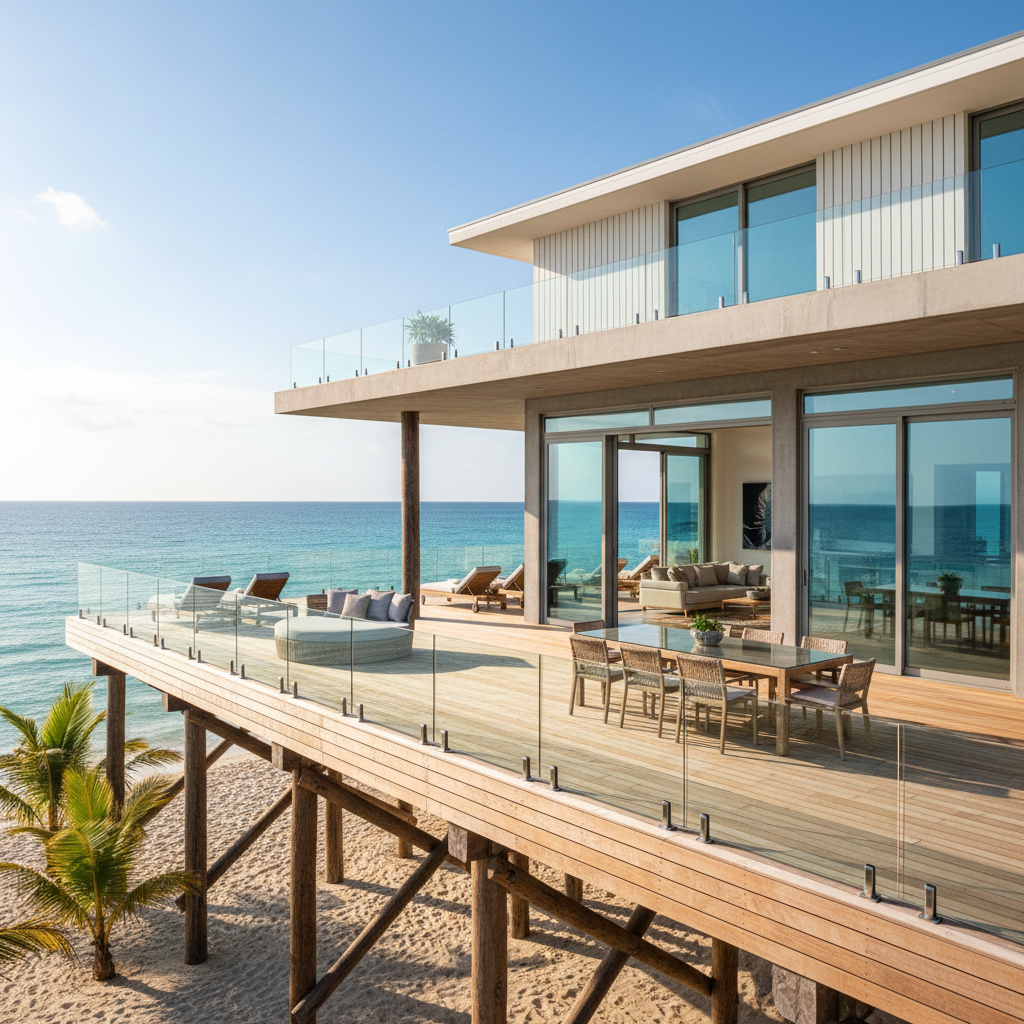
Hurricane Damage Diminution, Insurance Claim
After Hurricane Dorian, an insurer disputed the pre-storm value of a stilted oceanfront home, arguing the market already discounted hurricane risk. The owners needed an independent appraiser to establish a defensible pre-event value for their $1.2M claim.
Retrospective appraisal using sales data from the six months preceding the storm. Replacement-cost analysis for the elevated foundation system, seawall infrastructure, and storm-resistant glazing was calculated independently using RS Means coastal cost data and verified against three contractor bids.
Pre-storm value established at $1.85M. Insurance claim approved at full requested amount.
Divorce Valuation, Contested Waterfront
A family law court appointed Appraise as a neutral third-party appraiser for a Carbon Beach property where the parties' own appraisers had produced values $4.2M apart. The discrepancy centered on the legal status of a private beach easement and its contributory value.
Title research confirmed the easement was appurtenant, not personal. A dedicated paired-sales study of Carbon Beach transactions with and without private beach access isolated the easement premium at 22% of land value. Both parties' attorneys were provided full workfile access.
Court accepted our value without modification. Settlement finalized within 60 days of report delivery.

Jumbo Underwriting, Cantilevered Cliff House
A private bank was underwriting a $14M purchase-money loan on a Big Sur cliffside compound. Standard AMC appraisers declined the assignment citing lack of comparable sales. The lender needed a credentialed appraiser with documented experience in structurally unique coastal properties.
Comparable selection extended to architectural peers in Carmel Highlands, Pebble Beach, and Malibu, with adjustments for Pacific frontage linear footage, geotechnical certification status, and USGS landslide hazard zone classification. Structural engineering report reviewed and cost-to-cure for remediation items estimated.
Appraisal supported the full purchase price. Loan funded. Client closed on schedule.
Estate Planning, $40M Barrier Island Compound
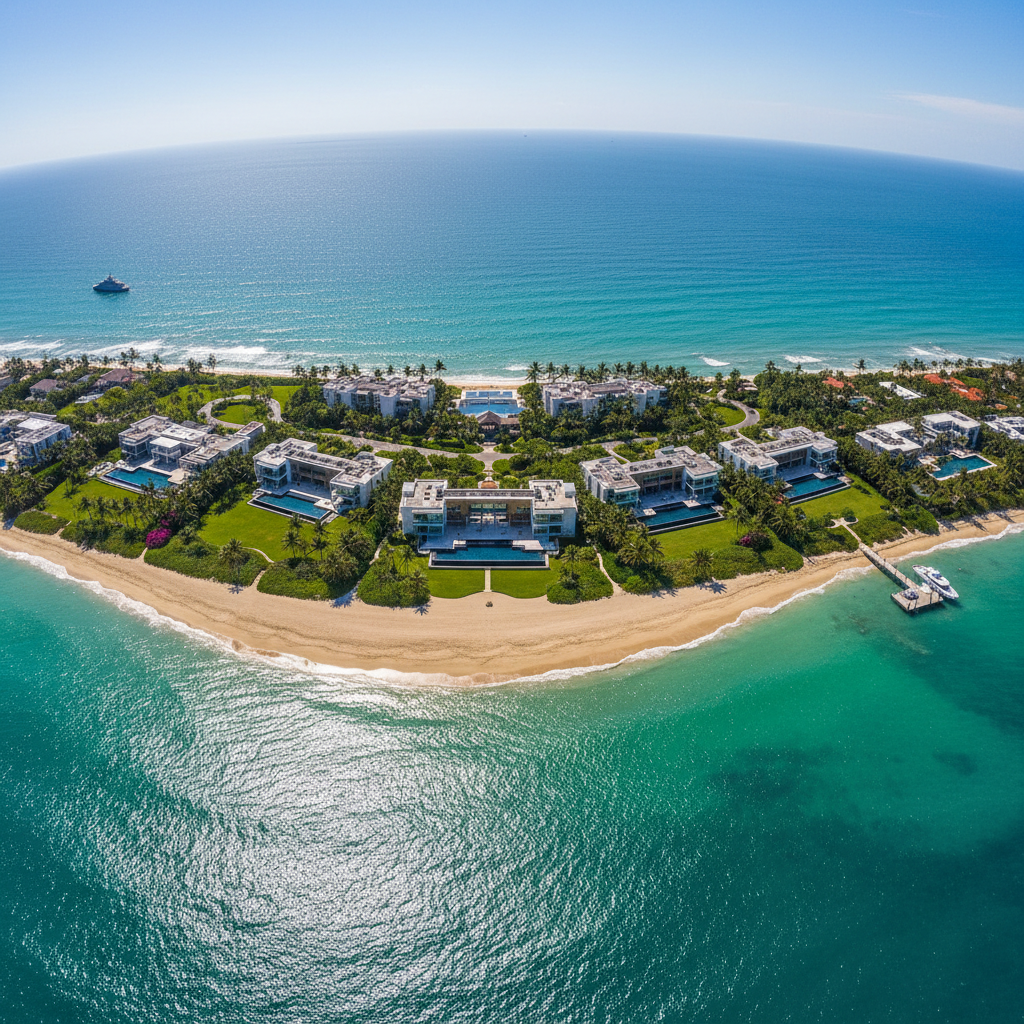
A Palm Beach family office engaged Appraise to establish fair market value for a barrier-island compound spanning four contiguous lots, a private dock, seawall, and a detached guest house, as part of a multi-generational estate plan with federal gift-tax implications.
The assignment required a highest-and-best-use analysis for potential lot subdivision, a separate seawall replacement-cost estimate ($2.1M), and a contributory-value analysis for the deep-water dock. IRS Revenue Ruling 59-60 standards applied throughout. Report prepared to withstand IRS challenge.
Estate plan filed. Gift-tax value accepted by IRS on first submission. No audit triggered.
"The tide line is not a poetic detail. It is the most volatile variable on the balance sheet."
The Number Has to
Hold Up in Court.
Every report we produce is prepared to withstand cross-examination by opposing counsel, IRS review, and lender underwriting scrutiny. Our credentials are not decorative.
MAI Designation
Member, Appraisal Institute — the highest credential in real estate valuation.
SRA Certification
Residential appraisal specialist, federally certified in all 50 coastal states.
FEMA NFIP Certified
Authorized to interpret flood-map amendments and elevation certificates.
Court-Qualified Expert
Accepted as expert witness in federal and state courts in FL, CA, MA, NC, NY.
Counted Twice. Defended Once.
Comparable Sales with Linear-Footage Adjustment
Every comparable is adjusted for water frontage measured to the inch — not acreage, not lot width. One linear foot of oceanfront on Carbon Beach is not the same as one linear foot in Clearwater.
LIDAR Elevation & Erosion Modeling
We overlay USGS LIDAR data against historical shoreline surveys to quantify bluff recession, beach width loss, and setback changes over time — translating geomorphology into dollars.
Replacement-Cost for Marine Infrastructure
Seawalls, docks, rip-rap revetments, and elevated foundation systems are appraised as independent improvements with their own depreciation schedules and replacement-cost estimates.
Flood-Zone Premium & Penalty Analysis
FEMA zone designation is modeled as a discrete value variable — not folded into a general 'market conditions' adjustment. AE versus X is not a footnote. It is a line item.
The Number They
Needed to Believe.

Coastal Appraisal Practice
In Coastal Value Appraised
Coastal Assignments Completed
Court & Lender Acceptance Rate
Schedule Your
Appraisal.
Inspection windows are available within 5–10 business days for most coastal markets. Complex assignments or remote barrier-island locations may require additional scheduling lead time.
What to Expect
Not Ready to Schedule?
Request a redacted sample report to see our methodology and format before committing.
Property Address
Enter the coastal property address. We'll confirm flood-zone designation and coastal-zone status.